Area report
Ilioupoli
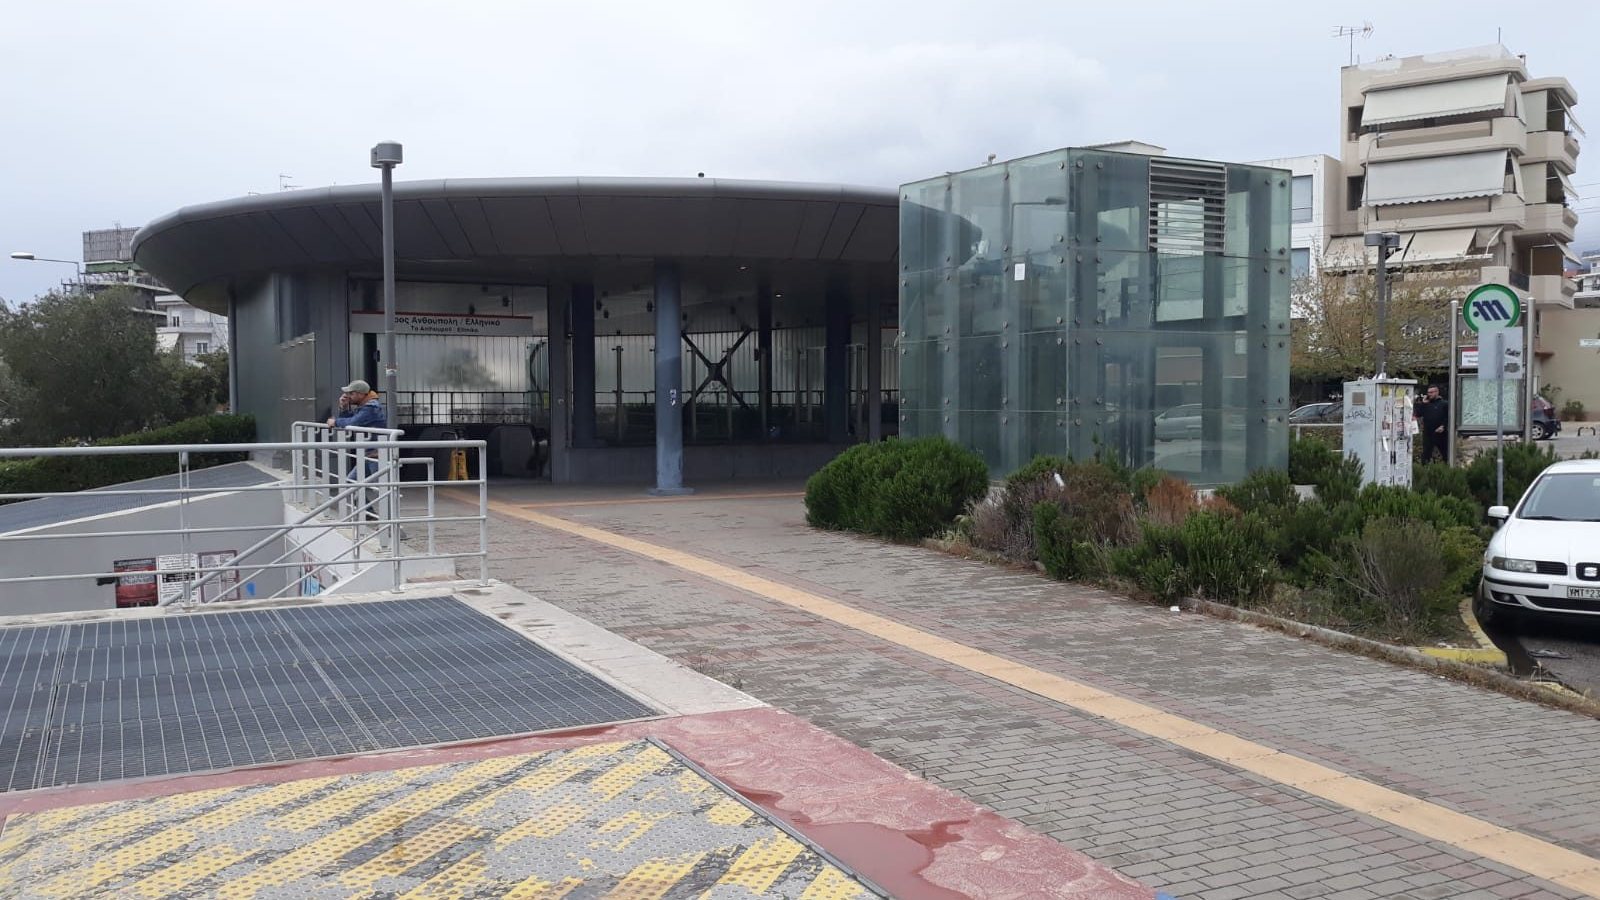
This report assesses the suburb of Ilioupoli and the southern Athens investment context at the foot of Mount Hymettus. It does not review a specific scheme or unit; it addresses location, amenities, tenant profile, the rental market and price trends at suburb level.
01Executive summary
Ilioupoli is an established residential suburb in the south-east of the Athens basin, set on the lower slopes of Mount Hymettus. It has roughly 76,700 residents (2021 census) and a settled, largely owner-occupied fabric of mid-rise apartment blocks, local high streets and green pockets that climb towards the mountain. It is not a tourist district. It is a place where people live, and that is what defines its investment character.
Three structural factors sustain residential demand. First, direct metro access: the suburb has its own station on Line 2, which runs through the city centre without a change. Second, proximity to the Athens Riviera: the coast and the Hellinikon redevelopment area lie a short distance to the south-west, and Line 2 continues there. Third, a green, calmer setting than the dense city core, which keeps the suburb attractive to long-term tenants and owner-occupiers.
For an investor, the defining feature is that demand rests on a resident population and commuter employment rather than on a tourism or short-let cycle. That translates into a defensive tenant base with comparatively low off-season vacancy risk and limited exposure to short-let regulation. The corollary is that the sharp value jumps seen in parts of central Athens and the coastal axis should not be assumed here; the suburb's profile is one of stable demand and capital preservation, not high yield.
- Suburb
- Ilioupoli (Ilioupolis) — southern Athens, foot of Mount Hymettus
- Character
- Established residential suburb; green, low-key, owner-occupier dominated
- Population
- About 76,700 (2021 census)
- Rail
- Own metro station on Line 2 (Red); about 1 km from the project area
- Centre of Athens
- Acropolis about 3.5 km
- Retail & leisure
- Athens Metro Mall about 1 km; open-air theatre about 500 m
- Schools & green space
- Schools about 50 m and a neighbourhood park about 60 m from the project area
- Culture & coast
- Stavros Niarchos Foundation Cultural Center about 5 km; Athens Riviera to the south-west
- Tenant base
- Singles and couples commuting by metro, young families, southern-coast employees
- Investment profile
- Defensive — steady demand, low seasonality
02Location and access
Ilioupoli lies about 3.5 kilometres from the Acropolis, on the south-eastern side of the basin where the city meets the pine-covered slopes of Mount Hymettus. It is connected to the centre chiefly by rail: the suburb has its own station on Metro Line 2, which serves the city centre and the southern coastal suburbs in the same line. Bus services feed the station from the upper parts of the suburb.
Distances and Journey Times
| Destination | Mode | Approximate time / distance |
|---|---|---|
| Metro station (Line 2) | On foot / short distance | ~1 km |
| Athens Metro Mall | Short distance | ~1 km |
| Schools and neighbourhood park | On foot | ~50–60 m |
| Open-air theatre | On foot | ~500 m |
| Acropolis | Car / metro | ~3.5 km |
| Stavros Niarchos Foundation Cultural Center | Car | ~5 km |
| Central Athens (Syntagma) | Metro, Line 2 (no change) | approx. 15–20 minutes |
| Southern coast and Hellinikon area | Metro, Line 2 / car | approx. 10–20 minutes |
| Athens International Airport | Car or metro with one change | approx. 50–70 minutes |
03Amenities and daily life
Everyday Services
The suburb meets its own daily needs: local high streets with cafés, bakeries and neighbourhood restaurants, supermarkets, schools at several levels and community sports facilities. The Athens Metro Mall, about one kilometre from the project area, adds a larger-format retail and leisure option without leaving the suburb's orbit.
Green Space and Outdoor Life
Mount Hymettus rises directly behind the suburb, and several small parks and open spaces sit within the residential fabric. For the project area, the documentation records a neighbourhood park about 60 metres away and an open-air theatre about 500 metres away. For tenants and owner-occupiers this is a quality-of-life advantage over the denser, more heavily built districts closer to the centre.
Culture and the Coast
The Stavros Niarchos Foundation Cultural Center, about five kilometres away, is the main cultural destination of the Athens Riviera. The coast itself, with its marinas and promenades, lies to the south-west, and the Hellinikon redevelopment area sits at the end of Line 2. Ilioupoli therefore offers a residential address with the coast within easy reach, at a lower entry price level than many coastal locations.
Reading the Suburb as an Investment
Depth of services. Rail, schools, retail and green space sit within the same short radius. That combination gives the suburb real everyday liveability, which supports longer tenancies.
Resilience of demand. The tenant base is tied to residence and commuting rather than the tourist cycle, which limits both seasonal vacancy and exposure to short-let regulation.
04Demographics and tenant profile
Ilioupoli's population is settled. Unlike central neighbourhoods with high short-term turnover, the suburb is made up of established households, many of them owner-occupiers, alongside a steady flow of younger tenants who value metro access and a calmer setting. That fabric also determines the character of rental demand.
| Tenant segment | Source of demand | Typical tenancy behaviour | Demand stability |
|---|---|---|---|
| Metro commuters | Line 2 to the city centre | Singles and couples, one-bedroom demand, 1–3 year tenancies | High |
| Young professionals | City-centre and Riviera employment | Seeking lower rents than the centre with rail access | High |
| Young families | Local schools, green setting | Long term, often moving up to larger flats | High |
| Southern-coast employees | Riviera and Hellinikon area | Medium to long term; depth depends on the pace of redevelopment | Moderate |
| Established local households | The suburb's own population | Mostly owner-occupied; low turnover | High |
| Tourist short-let | City tourism | Suburb is off the central tourist axes | Low |
The final row is included deliberately. Ilioupoli is not a natural suburb for tourist short-letting, and this should be read not as a shortcoming but as its function within a portfolio. In a market where short-let income is sensitive to regulatory change and to the tourism cycle, suburbs driven by long-term tenancies form the stabilising side of a portfolio.
Where One-Bedroom Demand Comes From
Single people and couples commuting by metro make the one-bedroom the primary product type in the suburb. At the same time, because the local resident population tends to seek larger apartments, the supply of small, energy-efficient new-build units is comparatively thin; much of the local stock consists of older, larger flats built several decades ago.
05Rental market and yield trend
The bands below are indicative figures for planning purposes, applying to new-build, high energy-class one-bedroom homes in the suburb. They are not a market measurement and must be verified separately against current, local rental evidence for the relevant unit type before any investment decision.
| Product type | Indicative monthly rent | Depth of demand | Vacancy risk |
|---|---|---|---|
| One-bedroom · new build · energy A · without parking | €650 – €800 | Broad | Low–Moderate |
| One-bedroom · new build · energy A · with parking | €700 – €880 | Broad | Low |
| Two-bedroom · new build · energy A | €900 – €1,150 | Moderate | Moderate |
Gross Yield Trend
In the established suburbs of southern Athens, gross rental yields run in a more measured band than in parts of the centre and the port axis. The reason is structural: because demand is stable, sale prices settle faster relative to rents. In practice this means a gross yield band of around 3% on list prices for new-build one-bedroom homes; after acquisition costs and operating expenses, the net figure sits materially below that.
06Price trend — market observation
The assessment below is a qualitative reading based on trends observed in Avla's Athens portfolio work; it does not substitute for index data or official statistics.
- Direction. Residential prices across Athens have trended upwards in recent years. In established southern suburbs such as Ilioupoli the movement has been steadier than in the centre and on the coastal axis, with fewer sharp steps.
- New-build premium. Because much of the local stock is older, new-build units with a high energy rating are priced at a clear premium per square metre over existing stock. That premium is partly justified by the difference in running costs and maintenance burden.
- Supply constraint. Ilioupoli is a built-out fabric. New schemes tend to arrive on small plots with few units, which reduces the likelihood of a short-term supply shock.
- Coastal spillover. The ongoing Riviera and Hellinikon redevelopment is a reference point for buyers looking for the coast at lower price levels. Whether, when and how far that translates into Ilioupoli prices cannot be assumed and should not be treated as a base case.
- Sensitivities. Interest rate conditions, construction costs and tax measures affecting foreign buyers can all determine price direction. The regulatory position should be verified in its current form before any purchase.
07Who it suits
Suited Investor Profile
- Stability-first investors. Appropriate for portfolios seeking low vacancy risk and predictable cash flow rather than a high headline yield.
- Long-term letting strategies. For investors wanting to reduce exposure to short-let regulation, the suburb's demand structure offers a natural hedge.
- Investors seeking a portfolio counterweight. In a portfolio holding tourism-sensitive assets in the centre or on the coast, Ilioupoli acts as ballast.
- Entry-level new-build buyers. For buyers who want an energy-efficient new build in southern Athens at a lower ticket than on the Riviera itself.
Less Suited Profile
- Buyers targeting short-term capital gains. The suburb has no rapid regeneration dynamic of its own; value growth is incremental.
- Investors focused on tourist short-letting. The suburb lies off the central tourist axes and nightly-let demand is limited.
- Investors seeking high gross yields. Yield bands in established southern Athens suburbs are measured; aggressive yield targets are not met in this geography.
08Swot — suburb level
Strengths
- Own station on Metro Line 2 — direct line to the centre and to the southern coast
- About 3.5 km from the Acropolis, yet green and calm on the foothills of Hymettus
- Settled population and owner-occupier fabric — low turnover, steady tenants
- Schools, parks, retail and an open-air theatre within a short radius of the project area
- Built-out fabric makes a large-scale supply shock unlikely
- Coast and the Riviera within easy reach at a lower entry price level
Weaknesses
- Limited tourist short-let potential — the income model depends on long tenancies
- Gross yield band more measured than in parts of the centre and the port axis
- Much of the local stock is older; new-build supply is selective
- No direct walking access to the sea
- Incremental value growth — unsuited to short-horizon exit scenarios
Opportunities
- Thin new-build supply in the one-bedroom segment — a competitive edge for well-specified small units
- The shift towards high energy-class stock: running-cost differences increasingly drive tenant choice
- Riviera and Hellinikon redevelopment drawing attention to the southern axis
- Metro-linked commuter demand from younger tenants priced out of the centre
Threats
- The direction of tax and regulatory measures affecting foreign buyers — current position must be verified before purchase
- The effect of interest rate and financing conditions on demand
- Construction cost inflation feeding through to new-build prices
- Changes in taxation and service charges applying to rental income
- The possibility that simultaneous local completions create short-term rental pressure
09Investment view
Investment View: Positive — Defensive
Ilioupoli suits investors seeking stable rental demand and incremental value growth in southern Athens. Its demand base rests not on the tourist cycle but on residence and metro commuting — a structural advantage that limits both vacancy risk and regulatory volatility. The corollary is a measured yield band and a suburb that does not produce rapid price jumps.
Resilience of Demand
A settled population, local schools and metro commuting provide independent sources of rental demand in the same suburb.
Accessibility
An own Line 2 station gives a direct, change-free link to the centre and the southern coast, widening the tenant pool.
Supply Discipline
The built-out fabric limits large-scale new supply; well-specified new one-bedroom homes remain comparatively scarce.